Clearance CLR-4542 · MRO891
MROAIR
MRO & AftermarketClearance sheet
Aircraft MRO Market Forecast to Grow at 9.8% CAGR Through 2030
The global aircraft MRO market is forecast to grow at a 9.8% CAGR through 2030, driven by aging fleets, tight shop capacity and surging engine overhaul demand.
Read-back
- The global aircraft MRO market is projected to grow at a 9.8% CAGR through 2030.
- The forecast reflects sustained demand across engine overhaul, airframe and component maintenance segments.
- Growth is supported by an aging global fleet and slow new-aircraft deliveries.
- Asia-Pacific and the Middle East are focal points for new MRO capacity investment.
- The projection was published in a market assessment distributed via EIN Presswire.
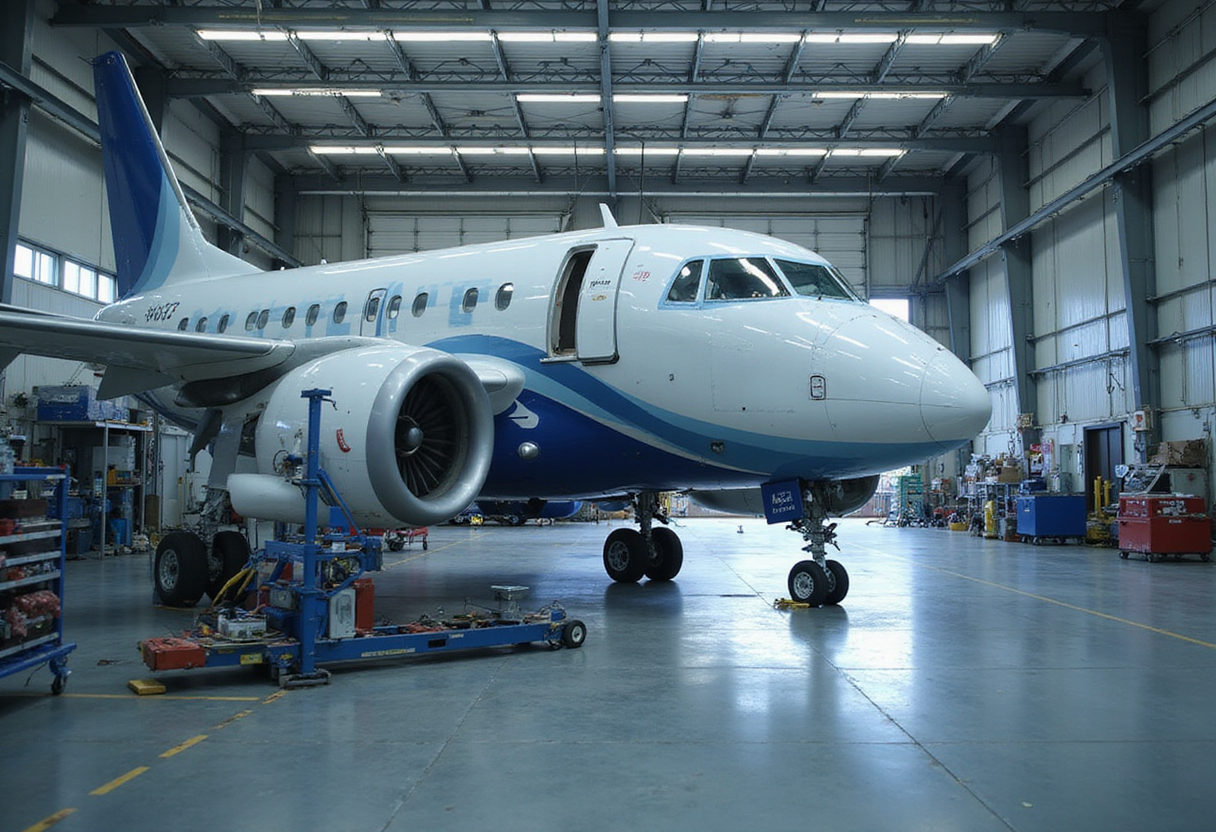
The global aircraft maintenance, repair and overhaul (MRO) market is projected to expand at a compound annual growth rate of 9.8% through 2030, according to a new market assessment distributed by EIN Presswire.
The forecast places MRO among the fastest-growing segments of commercial aviation, with growth running well above typical expectations for air traffic itself. That gap matters for operators: maintenance demand is driven less by traffic in any single year than by the age profile of the flying fleet, shop-visit intervals and the steady retirement — or deferred retirement — of older aircraft.
What is driving near-double-digit growth?
The forecast lands in a period when the MRO sector is already capacity-constrained. Engine shops, airframe heavy-check lines and component repair bays have reported long lead times as flying fleets age and new deliveries from Airbus and Boeing arrive more slowly than airlines planned.
Several structural forces support the 9.8% trajectory:
- An aging global fleet, as airlines keep mid-life aircraft in service longer while replacement deliveries lag backlog commitments.
- Rising demand for engine overhauls, the highest-value segment of the MRO market, driven by high-utilization narrowbody operations.
- Expanding maintenance demand in Asia-Pacific and the Middle East, where fleet growth and new home-market MRO investments are concentrated.
- Growing digital and predictive-maintenance adoption, which shifts work toward component and software-supported services.
Each of these factors ties directly to cost. When shop capacity is tight, airlines pay more for slots, wait longer for engine returns and fly fewer spare-backed aircraft — a burden that flows into capacity planning and network reliability.
How should the forecast be read?
A 9.8% CAGR is a strong claim, and market forecasts of this kind warrant scrutiny. Growth rates for MRO vary sharply across sub-segments: engine overhaul, line maintenance, components and airframe heavy checks rarely move in lockstep, and aggregate figures can mask divergent dynamics — such as a booming engine aftermarket alongside soft demand for widebody heavy checks.
Analysts and airline planners will want to verify the projection against verifiable indicators: shop-visit volumes at major providers such as Lufthansa Technik, ST Engineering, AAR and HAECO; backlog and turn-time disclosures from engine OEMs and their partner networks; and the pace of retirements, which releases or removes work from the system depending on direction.
The forecast also arrives as the industry's maintenance base is being rebuilt. Independent MRO providers, airline-owned shops and OEM service networks — including GE Aerospace, Rolls-Royce and Pratt & Whitney through their aftermarket programs — are all competing for the same technical talent, and labor availability remains a binding constraint on how fast forecast demand can actually be served.
What does this mean for airlines and lessors?
For airlines, sustained growth in maintenance demand implies continued upward pressure on maintenance cost per flight hour, particularly for operators of mature narrowbody fleets. For lessors, tighter shop capacity affects transition timelines and asset values, since a lease return requires a defined maintenance condition.
For the MRO providers themselves, a market compounding at nearly 10% annually through 2030 justifies the wave of hangar construction, engine-line expansion and joint ventures now visible across the Gulf, South Asia and Southeast Asia.
The test of the 9.8% figure will come in delivery and shop-visit data over the next several years: if OEM output recovers and fleet renewal accelerates, growth could moderate; if older aircraft keep flying, the aftermarket outlook strengthens.
via Google News: Aviation MRO (Source)
More from Grace Kim
Show full bio
News editor covering consumer brands and retail at Flightdeck Report.
380 articles
Same bay
- FDR942Aircraft MRO Market on Track for 9.8% Annual Growth to 2030 · October 12, 2026
- FDR603Airbus Points to New Routes as Engine of Asia-Pacific Narrowbody Demand · September 27, 2026
- FDR766Boeing's Fleet Renewal Test Hinges on Production, Certification · October 10, 2026
- FDR782Aviation MRO Finds an Old Lesson in Henry Ford's Playbook · September 30, 2026
- FDR352AAR to Acquire Majority Stake in MRO Holdings for $1.8 Billion · September 28, 2026