Clearance CLR-3078 · AIR645
AIRAIR
Air CargoClearance sheet
Airbus and Boeing delays raise fear of air cargo capacity crunch
Airbus and Boeing delivery delays are driving fears of an air cargo capacity crunch, tightening freighter supply and slowing belly capacity growth across key trade lanes.
Read-back
- Airbus and Boeing delivery delays are driving fears of an air cargo capacity crunch, the Financial Times reports.
- Delayed passenger aircraft deliveries slow growth in belly cargo capacity and starve freighter conversion programs of feedstock.
- Tighter freighter supply puts upward pressure on aircraft values, lease rates and cargo pricing.
- The capacity risk is forward-looking: demand growth may outrun supply growth if OEM output rates do not recover.
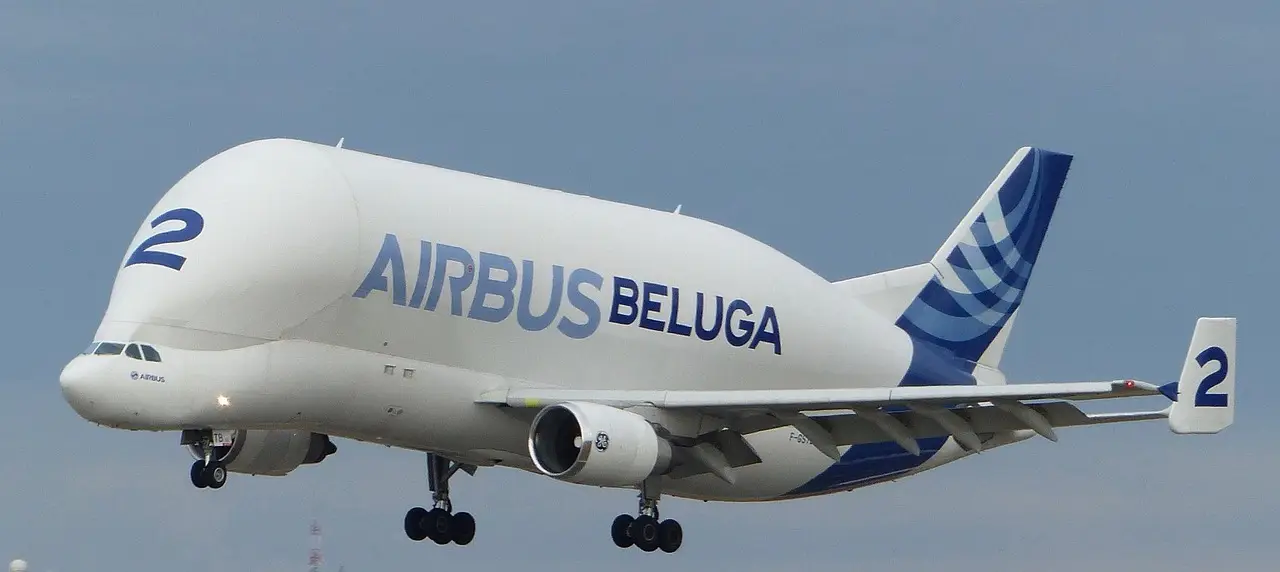
Delivery delays at Airbus and Boeing are driving fears of an air cargo capacity crunch, the Financial Times reports, as freight operators absorb the same production shortfalls that have slowed airline fleet renewal for the past several years.
The mechanism is straightforward. Air cargo capacity comes from two sources: dedicated freighters and the belly space (the cargo hold capacity beneath the passenger cabin) of scheduled passenger flights. Both channels depend on new aircraft arriving on time. When Airbus and Boeing push deliveries to the right, passenger belly capacity grows more slowly than planned, and freighter operators wait longer for the new-build and converted freighters that form the backbone of the dedicated fleet.
What does this change for cargo operators?
It removes the slack from the system. Freight forwarders and integrators have relied on a steady supply of factory-fresh freighters and converted passenger aircraft — a conversion being the process of stripping a retired airliner's interior and re-engineering it with a main-deck cargo door and reinforced floor — to expand capacity in line with e-commerce demand. Slower OEM output means fewer retired passenger airframes feed the conversion lines, because airlines keep older jets flying while their replacements sit undelivered.
That double squeeze is the core of the story. Delayed deliveries hold existing freight capacity in place, and they simultaneously starve the secondary market of feedstock for freighter conversions, the channel through which much of the mid-life widebody fleet re-enters service as cargo aircraft.
The two-channel dependency
Belly capacity is the larger of the two sources on many trade lanes, particularly transatlantic and intra-Asian routes where widebody passenger density is high. Dedicated freighters carry the oversize, heavy and time-critical freight that bellies cannot, and they dominate long-haul lanes with thin passenger service.
Both depend on the same manufacturers. Airbus widebody output and Boeing freighter programs — including the 777 freighter family and the 767-based freighter and conversion platforms — sit inside production systems that have struggled with supply chain, engine availability and certification timelines. A freighter that leaves the factory late delays not just one aircraft but the retirement of the older jet it replaces, which in turn delays that older jet's entry into a conversion program.
Cost and network consequences
For cargo operators, tighter capacity translates directly into higher aircraft values and lease rates. Lessors holding freighters gain pricing power as operators compete for the limited units available. For airlines, a capacity crunch in cargo hits a business line that has carried significant margin during periods of strong freight yields — a revenue stream many passenger carriers used to offset weak travel demand.
For shippers and forwarders, the practical question is pricing. If dedicated freighter capacity stays tight while belly growth stays slow, spot rates on affected lanes rise, and contract rates follow. The risk described in the reporting is not a collapse in available capacity but a market where demand growth consistently outruns supply growth because the delivery pipeline cannot keep pace.
Promised versus flying
As with any manufacturer-driven capacity story, the distinction between what is certified and flying and what is promised matters. Freight operators plan networks around delivery dates, and every slipped quarter compounds: a freighter arriving a year late is a year of lost tonne-kilometres on the lanes it was assigned to serve. The reporting frames the fear as forward-looking — operators watching the delivery schedule and seeing capacity growth fall short of what their freight forecasts require.
The test of how serious the crunch becomes sits in the delivery records themselves. If Airbus and Boeing recover planned output rates, the capacity gap narrows as parked orders arrive. If delays persist, freighter scarcity, firm lease rates and elevated spot pricing become the operating baseline for the cargo market through the current delivery cycle.
What comes next
The trajectory of the crunch now depends on two variables: OEM delivery execution over the coming quarters, and how quickly rising numbers of mid-life widebodies reach conversion lines once replacement aircraft finally arrive. Until one of those channels opens, cargo capacity growth stays capped by the production rates of the two manufacturers whose delays created the problem.
via Google News: Air cargo (Source)
More from Sophie Lindqvist
Show full bio
Senior reporter covering people, launches and day-to-day practice in Commercial aviation industry coverage at Flightdeck Report.
546 articles
Same bay
- FDR310Cargo Handler Consolidation Could Squeeze Airlines' Ground Costs · September 30, 2026
- FDR719Freight Giant Shifts Widebody Orders From Boeing to Airbus · September 29, 2026
- FDR877Air Cargo Demand Grew 4.4% in August as Load Factor Reached 46% · September 30, 2026
- FDR460Air cargo demand up 4.4% as freight rates climb · October 16, 2026
- FDR685IATA: Air Cargo Demand Climbs 4.4% in August as Capacity Slips · September 30, 2026